The Contract Was Bigger Than the Balance Sheet: How a $120K Painting Company Financed Its Way Toward $8M
A Nevada painting contractor won a hotel job it did not have the cash to start. A community lender financed 80 percent of the contract, then did it 18 more times. This is the mechanism, and what it takes for a founder to get a lender to bet on the opportunity instead of the paperwork.
By Pharoh Martin·
3 min read
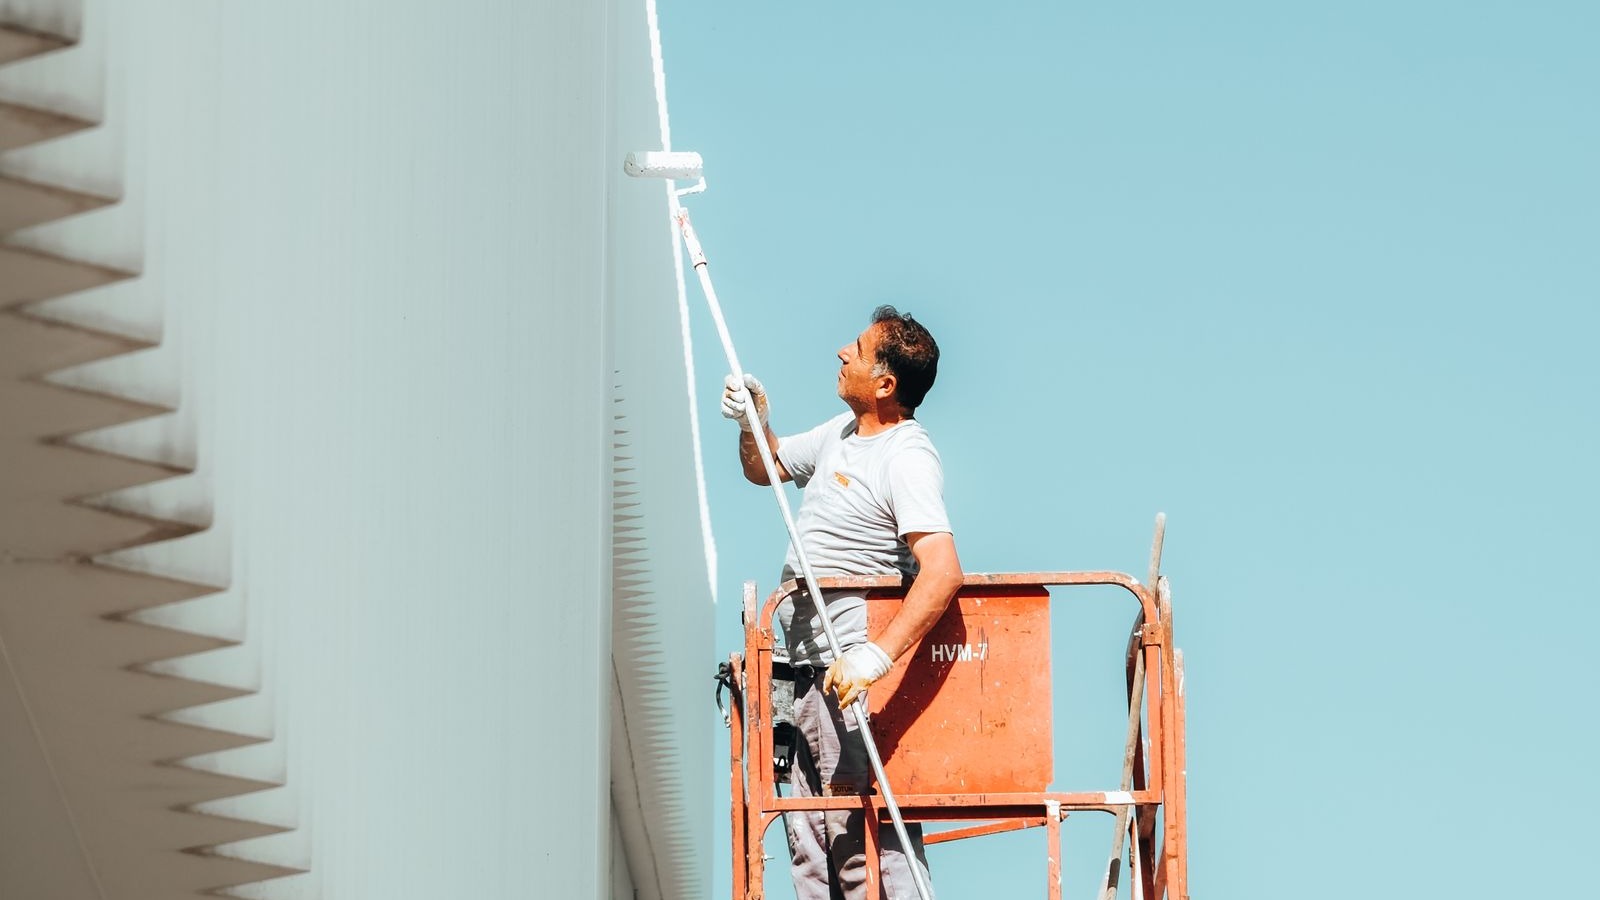
Every founder in a trade business knows this exact moment. The biggest contract of your life lands on the table, a hotel property, the kind of job that moves you from surviving to scaling, and the math does not work. Paint, equipment, and payroll are due in the next two weeks. The contract pays on completion milestones. Your bank account holds neither.
A Nevada painting contractor lived that moment at approximately $120,000 in annual revenue, with a signed hotel contract and no working capital to perform it. A conventional lender would have read the file in five minutes and passed. ACCESS CDFI, a community lender headquartered in Las Vegas, built a financing product around the contract instead.
ACCESS financed approximately 80 percent of the contract value. That advance bought the inventory and paid the new hires, the job got done, and the contract paid the lender back. Then it happened again. And again. ACCESS has completed 19 contract-financing transactions with that business, and its annual revenue is projected to hit $8 million this year. The story was told by ACCESS executive director Nic Steele at the Federal Reserve's State of Small Business Symposium.
How contract financing actually works
Contract financing is not a general-purpose loan. The signed contract is the collateral and the repayment plan at the same time. The lender evaluates the job: who the customer is, what the scope is worth, when payments land, and whether you can perform. If the deal holds up, the lender advances a percentage of the contract value so you can start, and gets repaid as the customer pays.
That structure flips the usual founder problem. A bank loan asks whether your past three years justify the money. Contract financing asks whether this job does. For a founder whose constraint is timing rather than talent, that is the difference between bidding on growth and watching it go to a bigger competitor. The lender's side of the structure, and what it costs a CDFI to underwrite this way, is broken down at CDFI Report.
What the lender needs to see
Steele's account of the deal points at what made this founder financeable, and none of it was a credit score. "We understood the business, identified the specific barrier preventing the new work, and designed a capital solution that matched the opportunity," he said.
Read that from the founder's chair and it becomes a checklist. A signed contract with a credible customer. A clear statement of the barrier, in this case the gap between starting costs and contract payments. A business the lender could understand, meaning books and numbers that could survive questions. ACCESS also wraps its lending in technical assistance, bookkeeping, planning, and operations support, and Steele credits that relationship for the outcome: the growth, he said, "didn't come simply from providing a loan."
Nineteen transactions is the other lesson. The first contract-financing deal is the hardest one you will ever close, because the lender is underwriting an opportunity and a promise. Perform, and the relationship compounds: each completed job is evidence, each repayment is a track record, and the lender who financed your first big contract becomes the first call on the next one. This founder's revenue did not grow 60-fold on one loan. It grew on a repeatable product and a lender who kept showing up.
The bottom line for founders
If your constraint is a signed opportunity you cannot afford to start, you do not have a revenue problem. You have a timing problem, and timing problems have specific lenders. CDFIs exist for the files conventional underwriting misreads, and contract financing is one of the sharpest tools they carry. Bring the contract, know your barrier to the dollar, and be ready for a lender who wants to understand the business, not just the score.
Filed under: contract financing, CDFI, working capital, small business growth, ACCESS CDFI, founder playbook
Sources
- Federal Reserve System, Fed Communities, "Small business ecosystem supports highlighted during Fed event," October 15, 2026 (reporting on the Federal Reserve's State of Small Business Symposium, including remarks by Nic Steele, executive director of ACCESS CDFI).
Related Coverage
The Newsletter
The week in Black entrepreneurship, in one email.
News, data, and playbooks. Free, weekly, no noise.